Is your company an MSME? Budget 2027 says yes and no.
Budget 2027 exempts “MSMEs” from two payroll changes. But the Budget measures MSME two different ways, and a company can pass one and may fail the other.
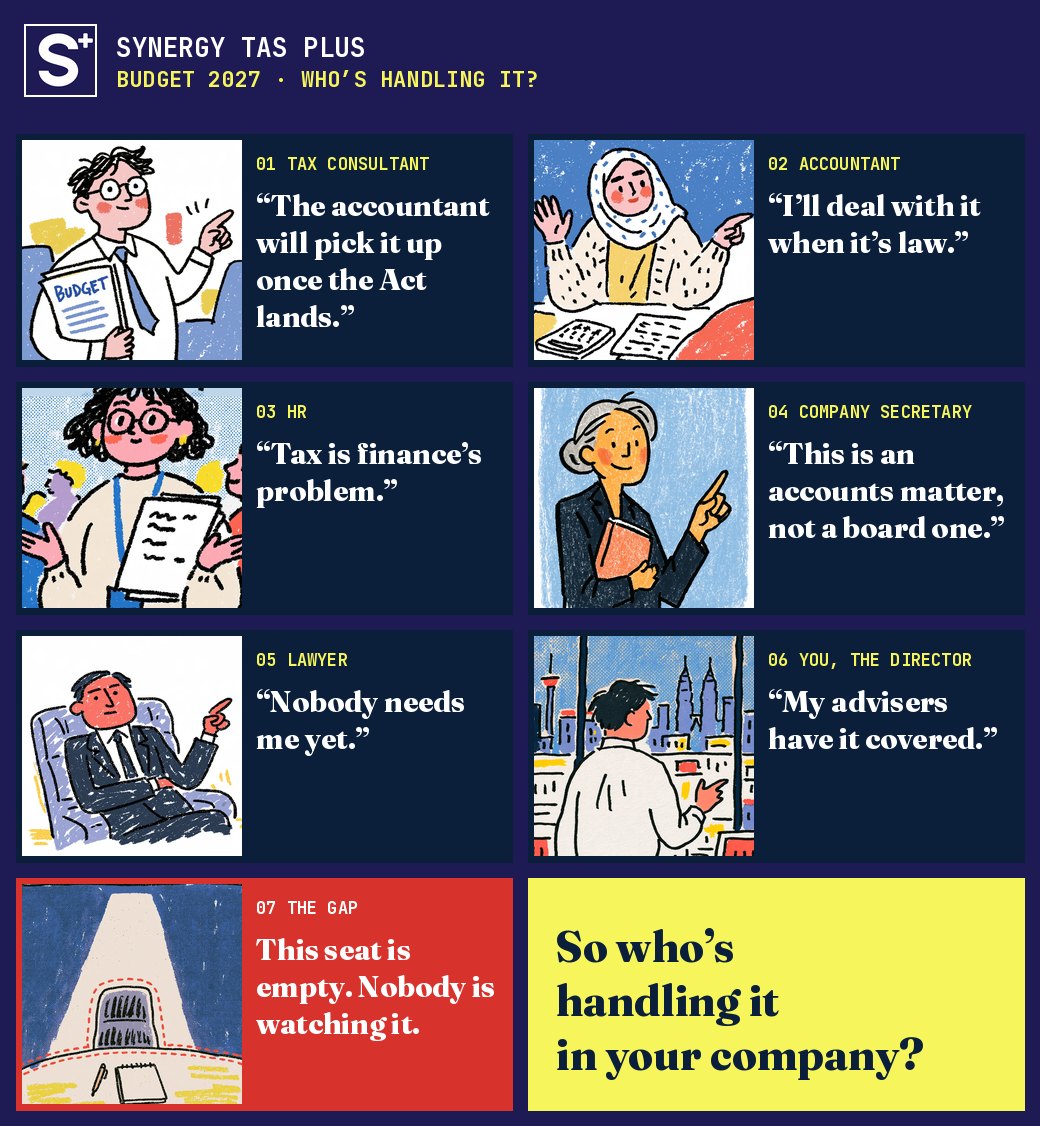
The short version
- Three payroll changes were announced on 9 October 2026. Only one is a tax change.
- The minimum wage exemption measures MSME by sales only (below RM50 million).
- The tax measures measure MSME by paid-up capital (RM2.5 million and below) and sales.
- Same company, two answers: exempt from one rule, likely caught by the other.
- None of it is law yet. That’s the window for tax planning.
What Budget 2027 announced for payroll
Minimum wage rises to RM2,000
Up from RM1,700 a month. A wage rule, not a tax rule. MSMEs with annual sales below RM50 million are exempt.
Source: Budget 2027 speech, para 32RM2,500 for semi-skilled workers and graduates
The first step of a wider wage reform. Who counts as “semi-skilled” hasn’t been defined. No exemption mentioned.
Source: Budget 2027 speech, para 32The cash salary rule
Salary is tax deductible only if paid through a financial institution or a cashless payment instrument under the Employment Act 1955. Today it’s deductible however it’s paid, cash included. MSMEs are excluded.
Source: Budget 2027 Tax Measures, Appendix 14Is my company an MSME under Budget 2027?
It depends which Budget rule you’re reading. The minimum wage exemption looks only at sales. The tax measures look at paid-up capital and sales. A company can pass one test and fail the other.
Take Mr. Lim. He runs a metal fabrication company in Klang: RM40 million in sales, 180 staff, RM5 million paid-up capital, and a site crew paid in cash every Friday. He asks his team one question: are we exempt?
His HR says “we’re an MSME, so we’re exempt.” For the minimum wage, that’s right. His accountant says “not for tax.” Under Appendix 11, that’s likely right too. Each is right about their own rule. Neither has the whole answer, and nobody has decided which one the company goes with.
if the cash salary rule treats him as an MSME, as the minimum wage rule does
extra tax a year from YA 2028 if it uses the tax definition, and his cash wages stop being tax deductible
Tax never stands alone: one payroll decision, six rulebooks
Paying a worker touches far more than tax. Each rulebook has its own authority, its own definitions and its own timing. When one changes, the others don’t move with it.
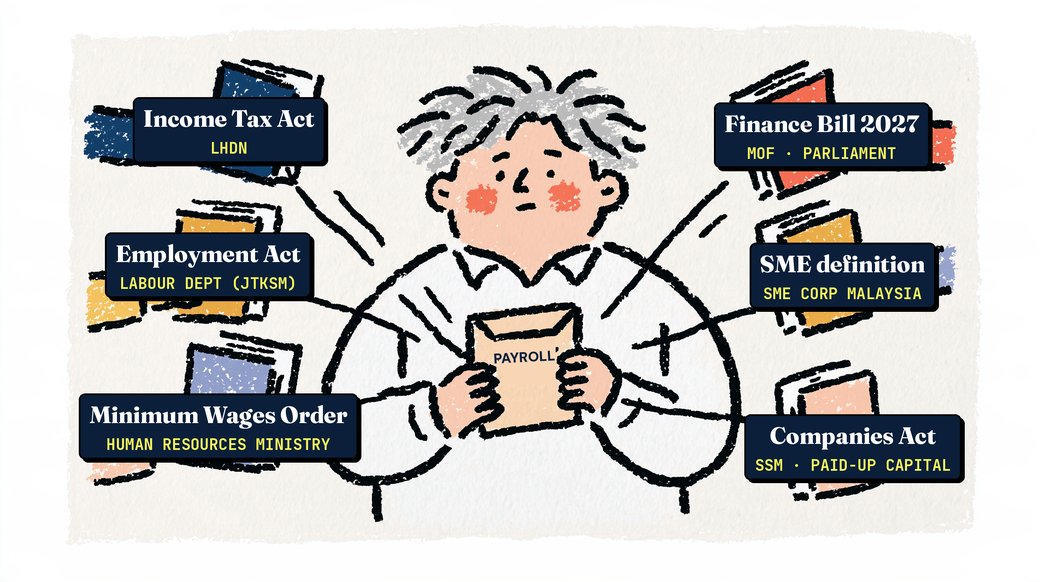
| Rulebook | Authority | The question it raises |
|---|---|---|
| Income Tax Act | LHDN | Is this salary still tax deductible? |
| Employment Act | Labour Department (JTKSM) | Can we pay in cash at all? Only if the worker asks in writing and the Director General approves. |
| Minimum Wages Order | Human Resources Ministry | What’s the floor, from when, and who is exempt? |
| SME definition | SME Corp Malaysia | Are we small, medium, or neither? |
| Companies Act | SSM | What’s our paid-up capital? Above RM2.5 million, the tax MSME test fails. |
| Finance Bill 2027 | MOF and Parliament | Not written yet. Which MSME definition will it use, and from when? This is the one that settles the rest. |
Wherever there is change, there is uncertainty. And it always sits where two rulebooks meet, and nobody owns that line.
The questions companies are asking right now
- “We do RM40m in sales. Are we exempt from the RM2,000 minimum wage or not?”
- “We’re signing off the 2027 payroll budget. Do we plan on RM1,700 or RM2,000?”
- “Our site crew want cash every Friday. Can we still do that, and will those wages still be deductible?”
- “Our fresh graduates start at RM2,300. Do we have to move them to RM2,500? From when?”
- “We’re part of a group. Do our sister companies’ sales count towards the RM50 million?”
The honest answer to most of these today is: not decided yet. The speech made a promise. The law that settles it hasn’t been written.
And that’s exactly where tax planning lives. While the rules are still open, a company has room to map out its position, anticipate the challenges, and decide which route to take, instead of waiting to be told.
The questions likely to reach the board
- Who owns it? Someone has to follow when each rule starts, which “small business” label (MSME) fits the company, and which workers are affected. If it’s “the team”, it’s nobody.
- Which workers? Who is still paid in cash? Under the Employment Act, that’s only allowed if the worker asked in writing and the Labour Department approved it. Who earns under RM2,000 today, and which graduates earn under RM2,500?
- Can the price carry it? If wages go up, does today’s selling price still cover the cost? Raise prices, accept a thinner margin, or change how the work is done: each has a trade-off, and 2027 contracts may already be agreed.
- How big are we, really? A company can count as “small” for the minimum wage and still not qualify as small for tax. That decides which rules apply and which tax rate it pays.
- When do we decide? Before a rule becomes law, the company has choices. After, it lives with the result. Are the decision and the reasons behind it documented in a way that protects the company?
Your accountant is reading the Ledger half of this post. Are you two on the same page?
What tends to surface when the rules land
1. Where each rule sits on the law route
| Announcement | Speech (9 Oct 2026) | Bill / draft order | Law | Start |
|---|---|---|---|---|
| RM2,000 min. wage | MSMEs below RM50m sales exempt (para 32) | NOT YET | NOT YET | June 2027 |
| RM2,500 min. wage | Semi-skilled workers and graduates (para 32) | NOT YET | NOT YET | Not given |
| Cash salary rule | Non-MSMEs: salary deductible only if paid cashless (para 33; App. 14) | NOT YET | NOT YET | YA 2028 |
2. Which MSME, three ways
- Tax MSME test (Income Tax Act; Budget Appendix 11): paid-up capital RM2.5m and below; annual sales not exceeding RM50m; related-company test; foreign-ownership condition.
- Minimum wage test (speech para 32): annual sales below RM50m. How sales are measured and whether related companies count is not yet set.
- SME Corp test: sales or staff by sector; large-group subsidiaries excluded. Three tests, possibly three answers.
3. How wages are actually paid
- Which pay elements go out by bank, e-wallet, cheque or cash? For anything outside an employee account, is the written request and Director General approval on file (s25, s25A)?
4. Cost and record
- How many staff sit under RM2,000, and what would the June 2027 rise cost each month if the company isn’t exempt?
- Are the board’s decision and the considerations behind it documented, with an owner and a review date?
It’s your name on the accounts. Not your tax adviser’s.
Tax isn’t paperwork you hand off. It’s a cost that comes straight out of your cash flow and your profit. Your tax agent usually arrives after year end. They weren’t there when the transaction was made. You were.
By then the record is already written. Nobody can go back and turn cash wages into bank transfers. That’s why the safeguard has to go in at the right time, while there are still options to weigh and the decision stays in your hands.
Most companies know keeping documents is a duty. Fewer see it as a tool.
Which one they become is decided on the day of the transaction, not at the audit.
Be in the know. Manage your own risk, instead of relying on luck.
Read it yourself: the official text
Frequently asked questions
Who is exempt from the RM2,000 minimum wage?
When does the cash salary tax rule start?
Can a company still pay salary in cash?
Why can a company be “small” for minimum wage but not for tax?
Is a Budget announcement already law?
Where we come in
You don’t need to read every Finance Bill or know every rulebook. You need someone who knows the law and translates it into practical steps: where the risk sits and what needs safeguarding, what has to be done now, and whether to change course or prepare for when the law lands.
Budget 2027 seminar with Dr. Choong Kwai Fatt
Bring your MSME question, your payroll question, your cash wages question. Walk out with an answer you can put in the board minutes.
Kuala Lumpur · 15–17 December 2026 · The Westin Kuala Lumpur
Johor Bahru · 26–28 January 2027 · DoubleTree by Hilton Johor Bahru
HRDCorp claimable · KL early bird until 13 November 2026 · Download the full payroll guide (PDF)
This article is general information, not legal or tax advice. It describes announcements made in the Budget 2027 speech on 9 October 2026, which may change before they become law. Mr. Lim’s company is an illustrative composite. Sources: Budget 2027 speech (Ministry of Finance), paragraphs 32, 33 and 127; Budget 2027 Tax Measures, Appendices 11 and 14; Employment Act 1955, sections 25 and 25A. Confirm your own position with a licensed tax agent before acting.